Tax News and Insights
Legislative updates, case law analysis and insights from our team of experts.
54 articles found · Page 1 of 6
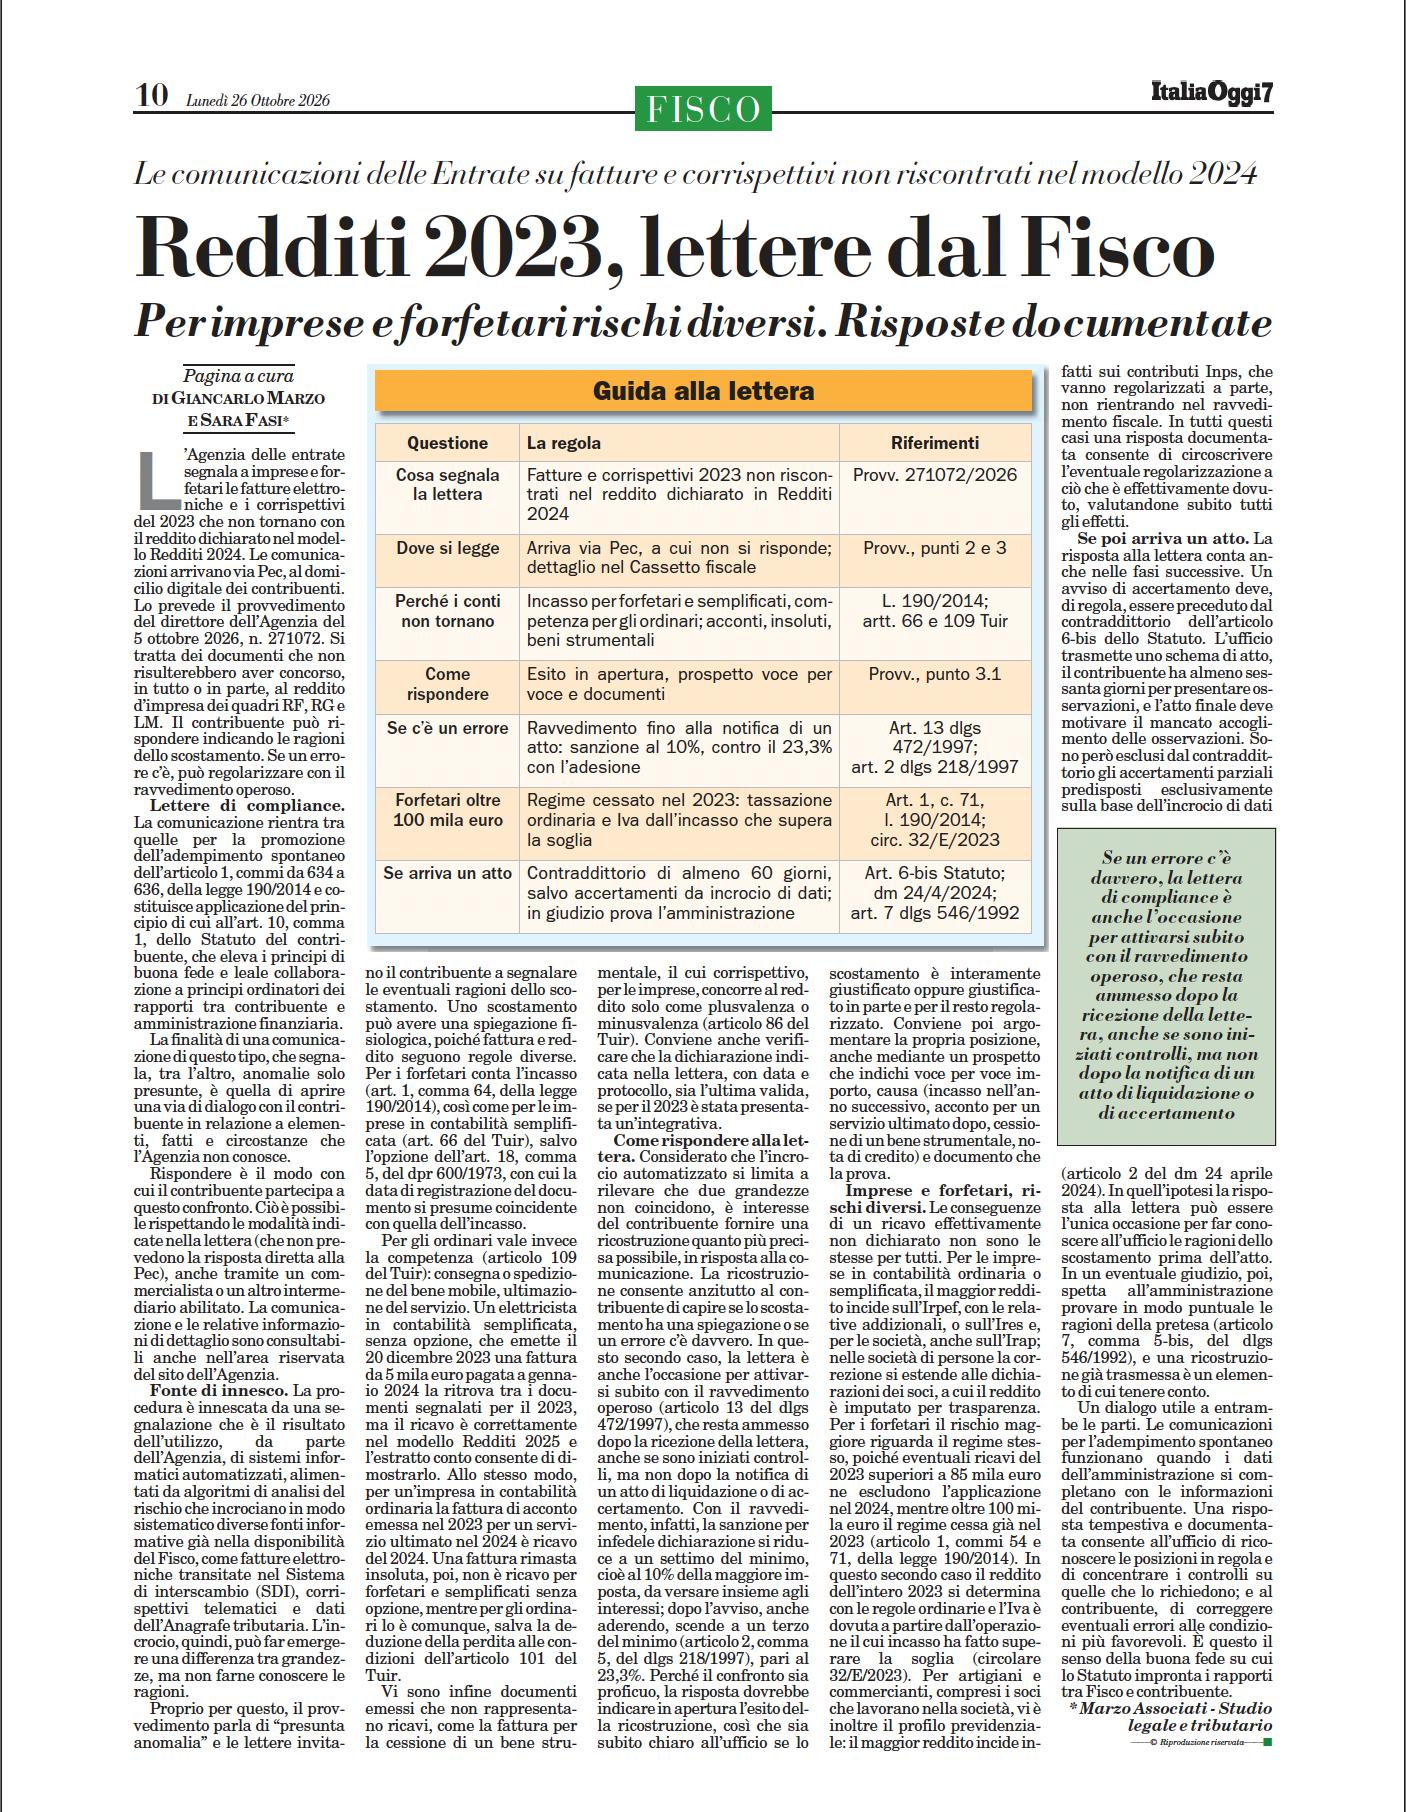
Compliance letters on 2023 revenue: how to respond to the Italian Revenue Agency (Agenzia delle Entrate)
The Italian Revenue Agency (Agenzia delle Entrate) flags to businesses and flat-rate taxpayers 2023 invoices and receipts not reflected in Redditi 2024. What to check, how to respond and when to use voluntary disclosure (ravvedimento operoso).

Trusts and creditors: when a property may be sold at auction
Placing a property in trust does not make it untouchable: Order No. 16957/2026 of the Italian Supreme Court (Corte di Cassazione) clarifies when a creditor's avoidance action defeats asset segregation and why even a change of trustee does not stop enforcement.

Dividends, Charitable Trusts and Foundations: the Shift by the Italian Supreme Court (Corte di Cassazione)
In its twin judgments nos. 16281 and 16284 of 26 May 2026, the Italian Supreme Court (Corte di Cassazione) holds that a charitable trust is functionally comparable to a foundation: for Italian dividends, what matters is the purpose pursued, not the legal form.

Commercial irrationality: not enough on its own
A departure from market value is no longer sufficient to justify an adjustment: Article 24 of the Omnibus corrective decree codifies scrutiny of commercial irrationality and requires further serious, precise and consistent circumstantial evidence.

Freedom in Generational Transfers
Recipients of tax-exempt shares may contribute them to a personal holding company: tax ruling (risposta a interpello) no. 152 of 31 July 2026 clarifies that the five-year requirement attaches to control, not to ownership of the individual shares.

Black list: the calculations need revisiting
The substitute tax for rebasing black list shareholdings rises to 36%, with instalment payments excluded: the changes in the draft Omnibus corrective decree and the need for a case-by-case cost comparison.
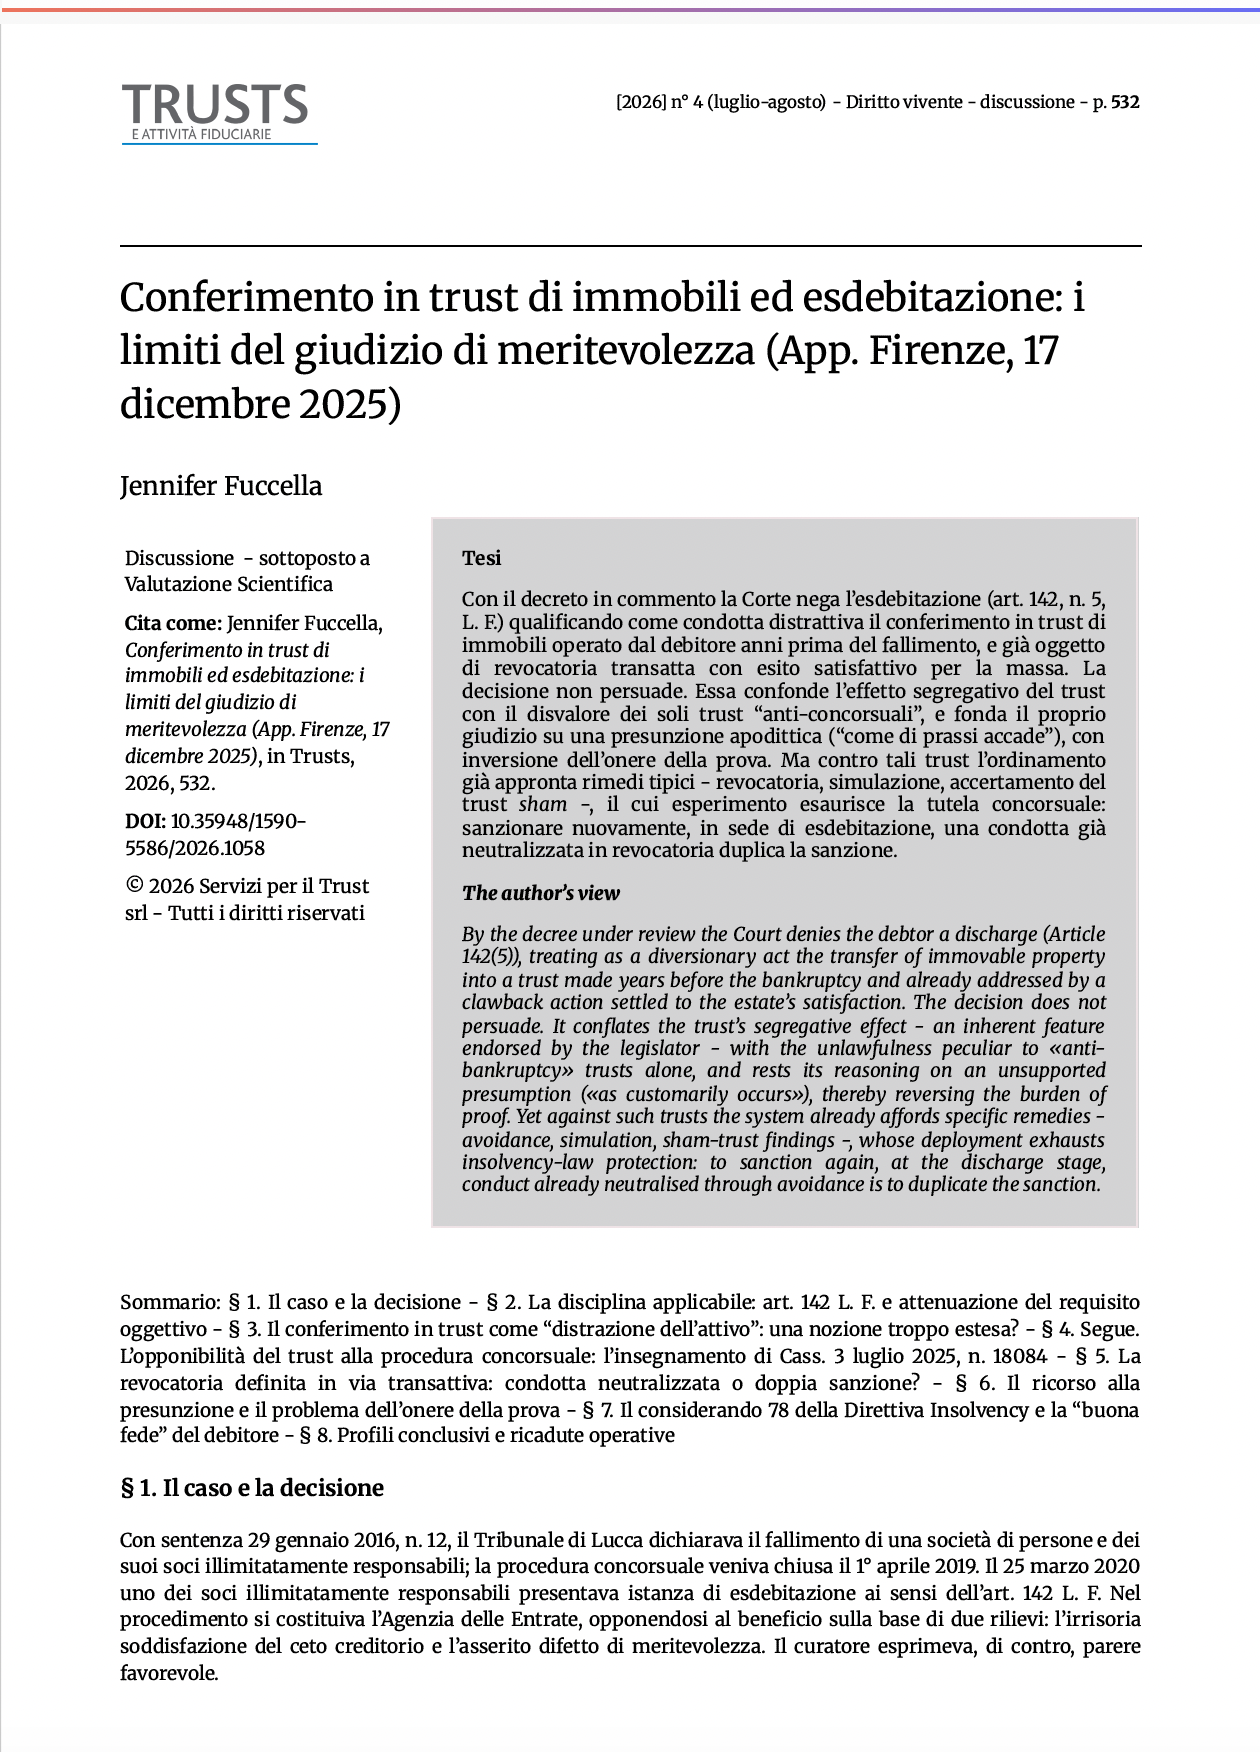
Transfers of immovable property into trust and discharge from debts: the limits of the assessment of deservingness (Florence Court of Appeal, 17 December 2025)
In the decree under review, the Florence Court of Appeal denies discharge from debts (Article 142, no. 5, L. F.), characterising as asset diversion the debtor's transfer of immovable property into a trust years before bankruptcy, which had already been the subject of an avoidance action settled to the satisfaction of the estate.
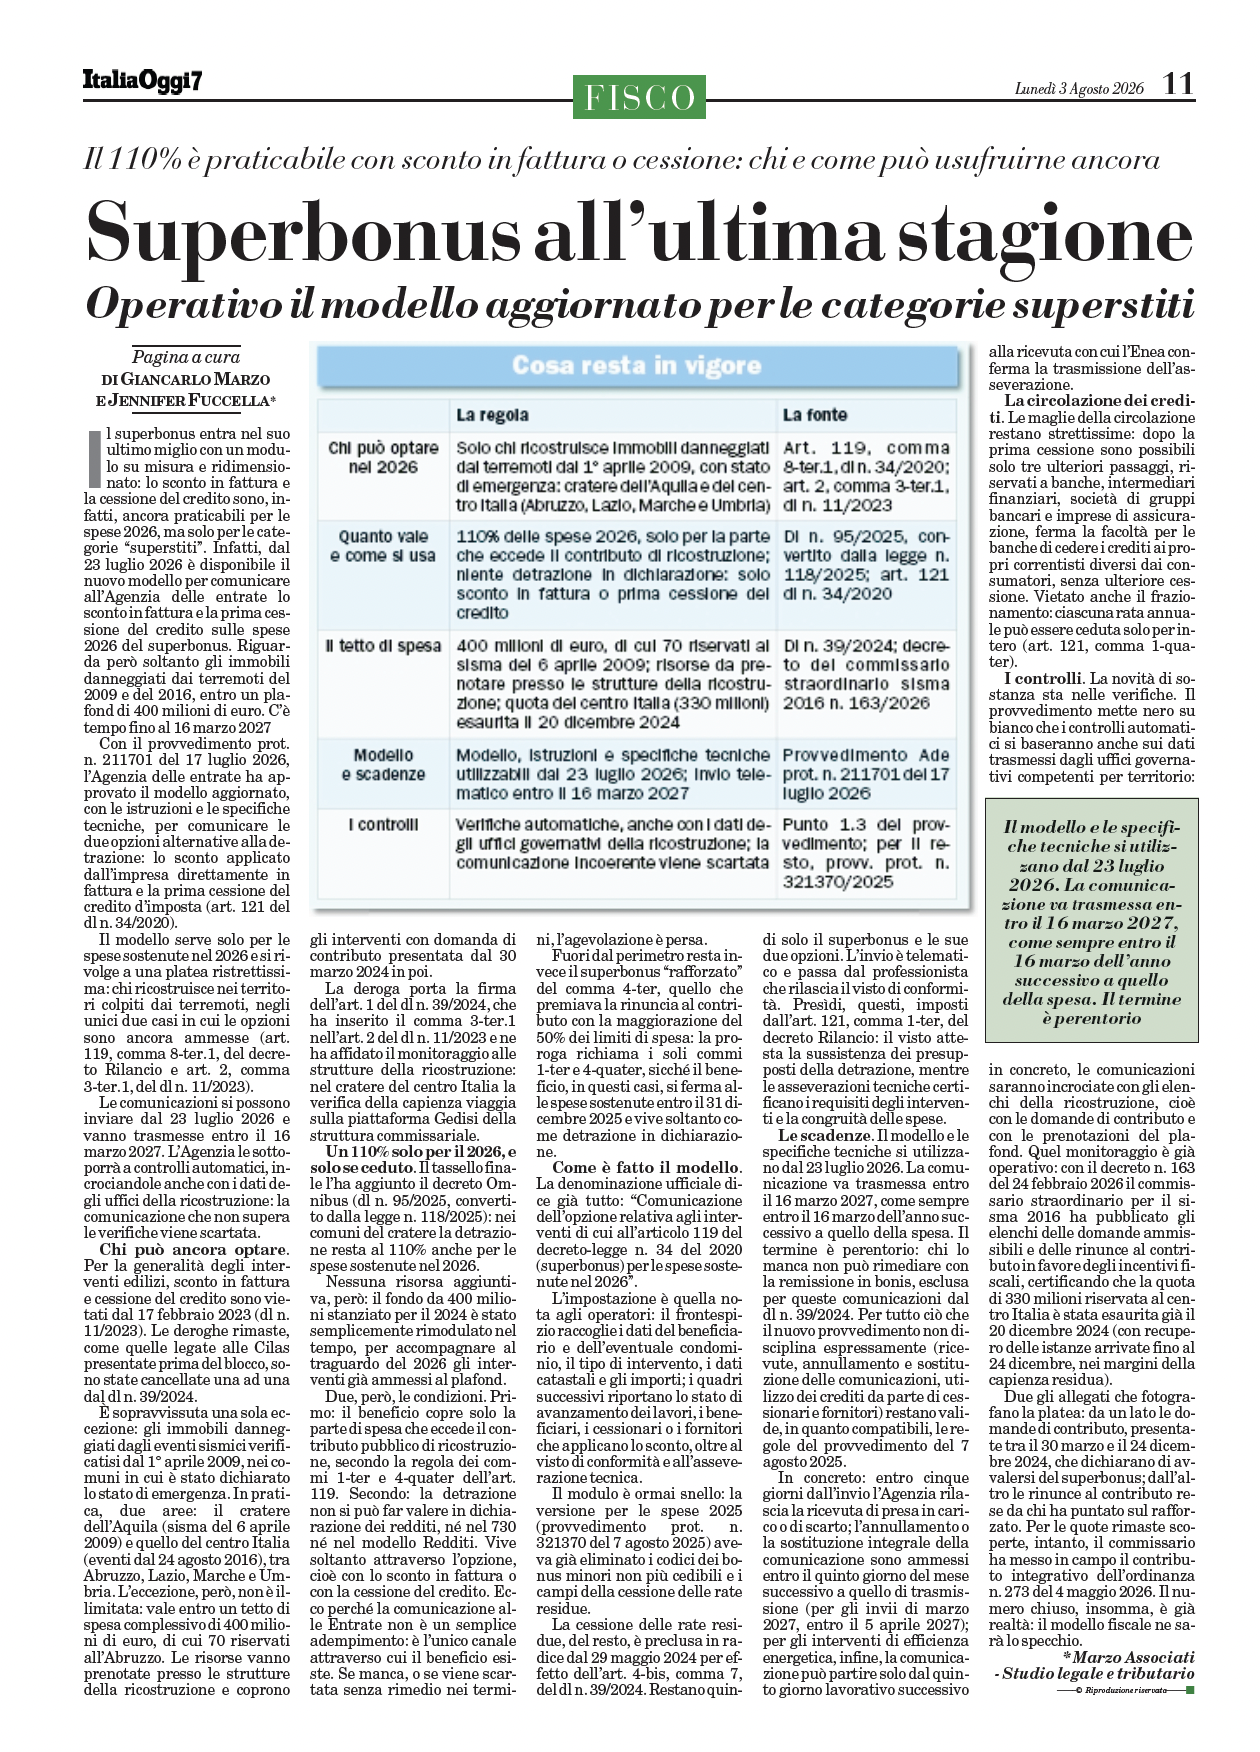
Superbonus in its final season: updated form now available for the remaining categories
Since 23 July 2026, a new form has been available for notifying the Italian Revenue Agency (Agenzia delle Entrate) of invoice discounts and the first transfer of tax credits for 2026 superbonus expenditure: it concerns only properties damaged by the 2009 and 2016 earthquakes, within a €400 million funding ceiling.
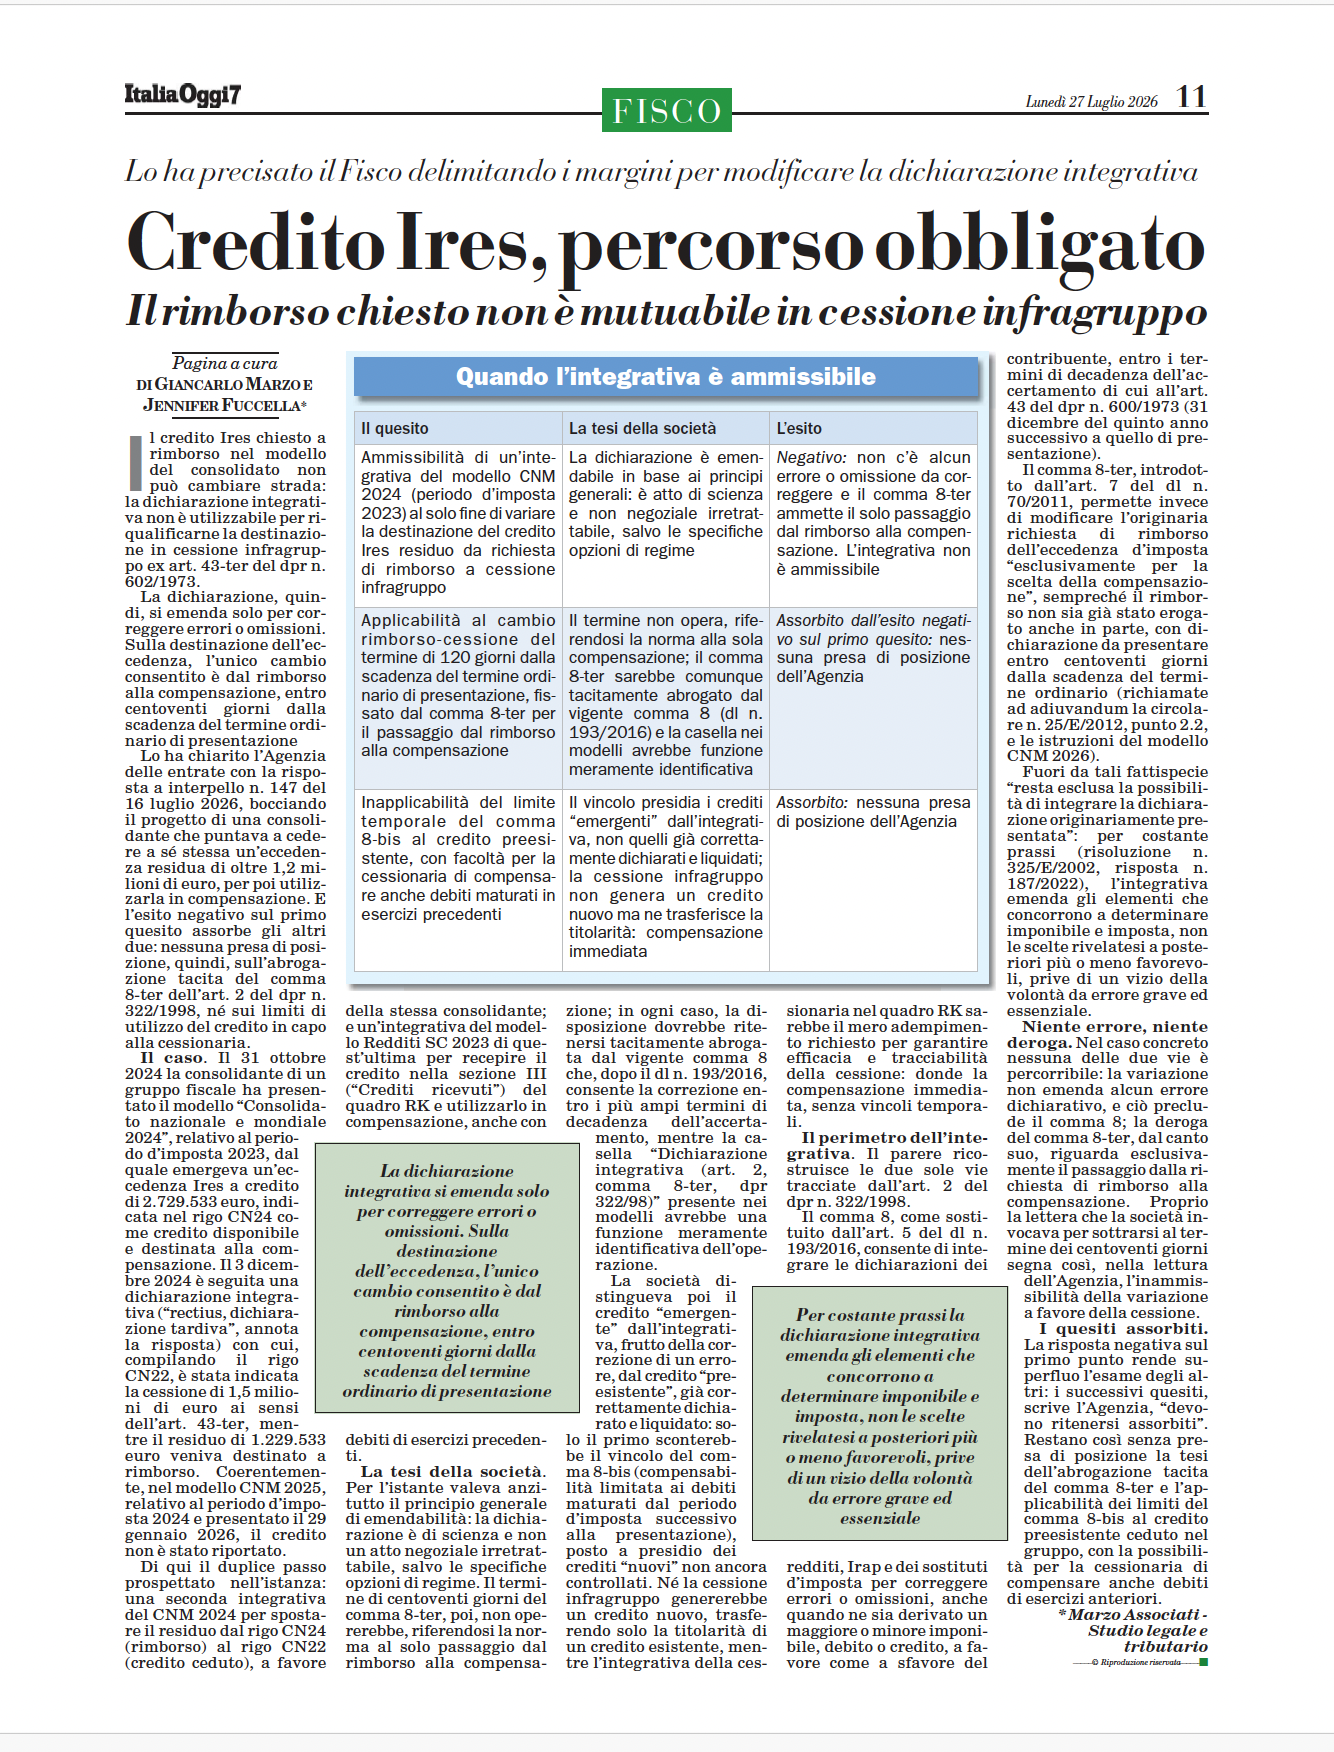
Corporate income tax (IRES) credit, a prescribed route: a refund claim cannot be converted into an intra-group transfer
In tax ruling (risposta a interpello) no. 147 of 16 July 2026, the Italian Revenue Agency (Agenzia delle Entrate) clarifies that a corporate income tax (IRES) credit claimed as a refund in the consolidated tax return cannot be reclassified as an intra-group transfer under art. 43-ter of dpr n. 602/1973 through an amended return.
All Insights Articles
- Compliance letters on 2023 revenue: how to respond to the Italian Revenue Agency (Agenzia delle Entrate)
- Trusts and creditors: when a property may be sold at auction
- Dividends, Charitable Trusts and Foundations: the Shift by the Italian Supreme Court (Corte di Cassazione)
- Commercial irrationality: not enough on its own
- Freedom in Generational Transfers
- Black list: the calculations need revisiting
- Transfers of immovable property into trust and discharge from debts: the limits of the assessment of deservingness (Florence Court of Appeal, 17 December 2025)
- Superbonus in its final season: updated form now available for the remaining categories
- Corporate income tax (IRES) credit, a prescribed route: a refund claim cannot be converted into an intra-group transfer
- Trusts and property purchases: when the price-value method applies (Treviso Tax Court no. 288/2025)
- Cross-border workers, a distinction in the regime: Bank of Italy employees in France are taxed only in Italy
- Non-deductible pro-rata VAT and IRAP: accruals, not cash
- Price-value and trusts: why an individual trustee can (and should) use it
- Is a debt discharge order subject to proportional or fixed tax?
- Trust beneficiary and removal of s.r.l. directors (Court of Rome, 16 January 2026)
- Seasonal workers: standard IRES calculations
- Second Insolvency Directive: Access to Trusts Without Prior Notice
- Marzo Associati at the Luiss Guido Carli Career Day
- Single Betting Tax: Italian Supreme Court (Corte di Cassazione) 2026 | Marzo Associati
- VAT Adjustments and Reverse Charge: The Italian Supreme Court Blocks Cashback Refunds
- Debt Restructuring and Tax: A Bar on Post-Approval Assessments
- How to lawfully avoid paying tax payment notices: 2026 guide
- Limitation periods for a tax payment notice (cartella): time limits, calculation and how to invoke them in 2026
- Trusts and the Italian Supreme Court (Corte di Cassazione): Acts Ineffective Without Express Clauses
- Rottamazione Quinquies 2026: eligibility, savings and deadlines
- Tax Payment Notice Instalment Plans 2026: 120 Instalments, Lapse and New Rules
- Holding Companies: Contributions and Gifts Do Not Constitute Abuse
- Bank account attachment by the Italian Tax Collection Agency: how to stop it
- Additional 2025 single SEZ tax credit: how to access it from 15 April 2026
- Administrative car immobilisation: how to have it lifted, timescales and costs in 2026
- Third-Party Statements and Synthetic Tax Assessments: Proof or Circumstantial Evidence? The Italian Supreme Court (Corte di Cassazione) in 2026
- Non-deductibility of legal costs for directors’ criminal defence: a further rejection by the Italian Supreme Court (Corte di Cassazione)
- Minor heirs: immediate obligation to file income tax returns, tax authorities do not await the inventory
- Trusts and Creditors: When Asset Protection Is Not Enough
- Bank Account Assessments and Relatives’ Accounts: The Italian Supreme Court (Corte di Cassazione) Confirms the Reversal of the Burden of Proof
- Rottamazione-quinquies: scope, effects and systemic issues
- Capital gains in business income: the end of "generalised" spreading
- Defects in Service of a Tax Payment Notice (cartella): When It Is Void
- Ex officio cancellation of collection rolls: limits on deemed consent for procedural defects
- Short-term lets and Airbnb: from 2026, three homes trigger VAT registration
- Suspending a Tax Payment Notice (cartella): 3 Legal Options in 2026
- Erroneous Tax Payment Notice: How to Challenge a Debt Not Owed
- Italian Supreme Court (Corte di Cassazione) 1667/2026: notices to shareholders, attachments are optional and the duty to state reasons can also be satisfied by reference
- Corporate interposition and closely held companies: profits go to the actual shareholders
- Tax Payment Notice (Cartella) Addressed to a Deceased Person: Must the Heirs Pay?
- Difference Between a Tax Payment Notice (cartella) and a Tax Assessment Notice
- 2026 Budget Law: Tax Changes for Businesses and Professionals
- Trusts and Generational Succession: A Practical Guide
- International Tax Planning: Opportunities and Risks
- First-home tax relief for AIRE registrants: the concept of "activity" expands to include study and volunteering
- Losses on debts in insolvency proceedings: the Italian Supreme Court (Corte di Cassazione) sets the "time window" for deductibility
- Public Gambling Reform: What Changes for Concession Holders
- Italian Supreme Court (Corte di Cassazione): Key Judgment on Transfer Pricing
- ADM: New Guidelines for Online Gaming Operators