
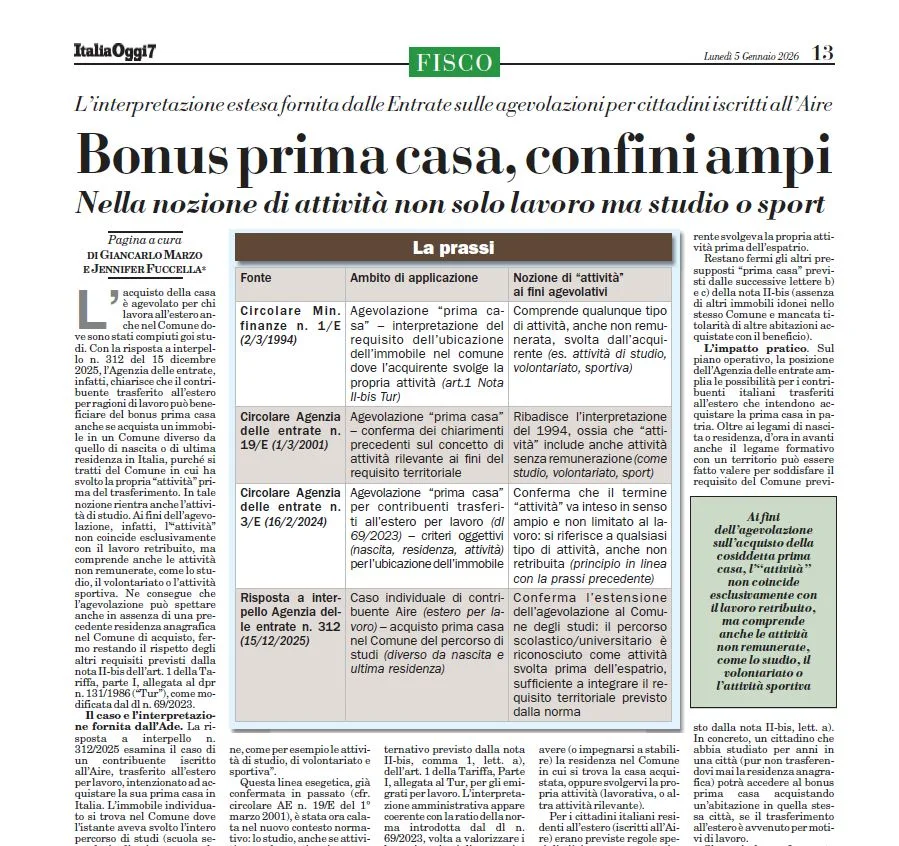
First-home tax relief for AIRE registrants: broadening the concept of "activity"
Italian citizens registered with AIRE who intend to purchase a home in Italy can now benefit from a broader interpretation of tax relief for a first home. In tax ruling (risposta a interpello) no. 312 of 15 December 2025, the Italian Revenue Agency (Agenzia delle Entrate) provided important clarification on the territorial requirement, facilitating access to "first-home tax relief".The broader concept of "activity" for access to first-home tax relief
The legislation (Note II-bis to Article 1 of the Tariff, Part I, annexed to dpr n. 131/1986) provides relief for Italians working abroad, provided that the property is located in the municipality in which the purchaser carried out their "activity" before moving abroad. The Italian Revenue Agency (Agenzia delle Entrate) clarified that the concept of "activity" is not limited exclusively to paid work. The definition includes a wide range of pursuits, including unpaid ones, which demonstrate a connection with the area. These include:- Courses of study (at school or university)
- Volunteering activities
- Sporting activities


