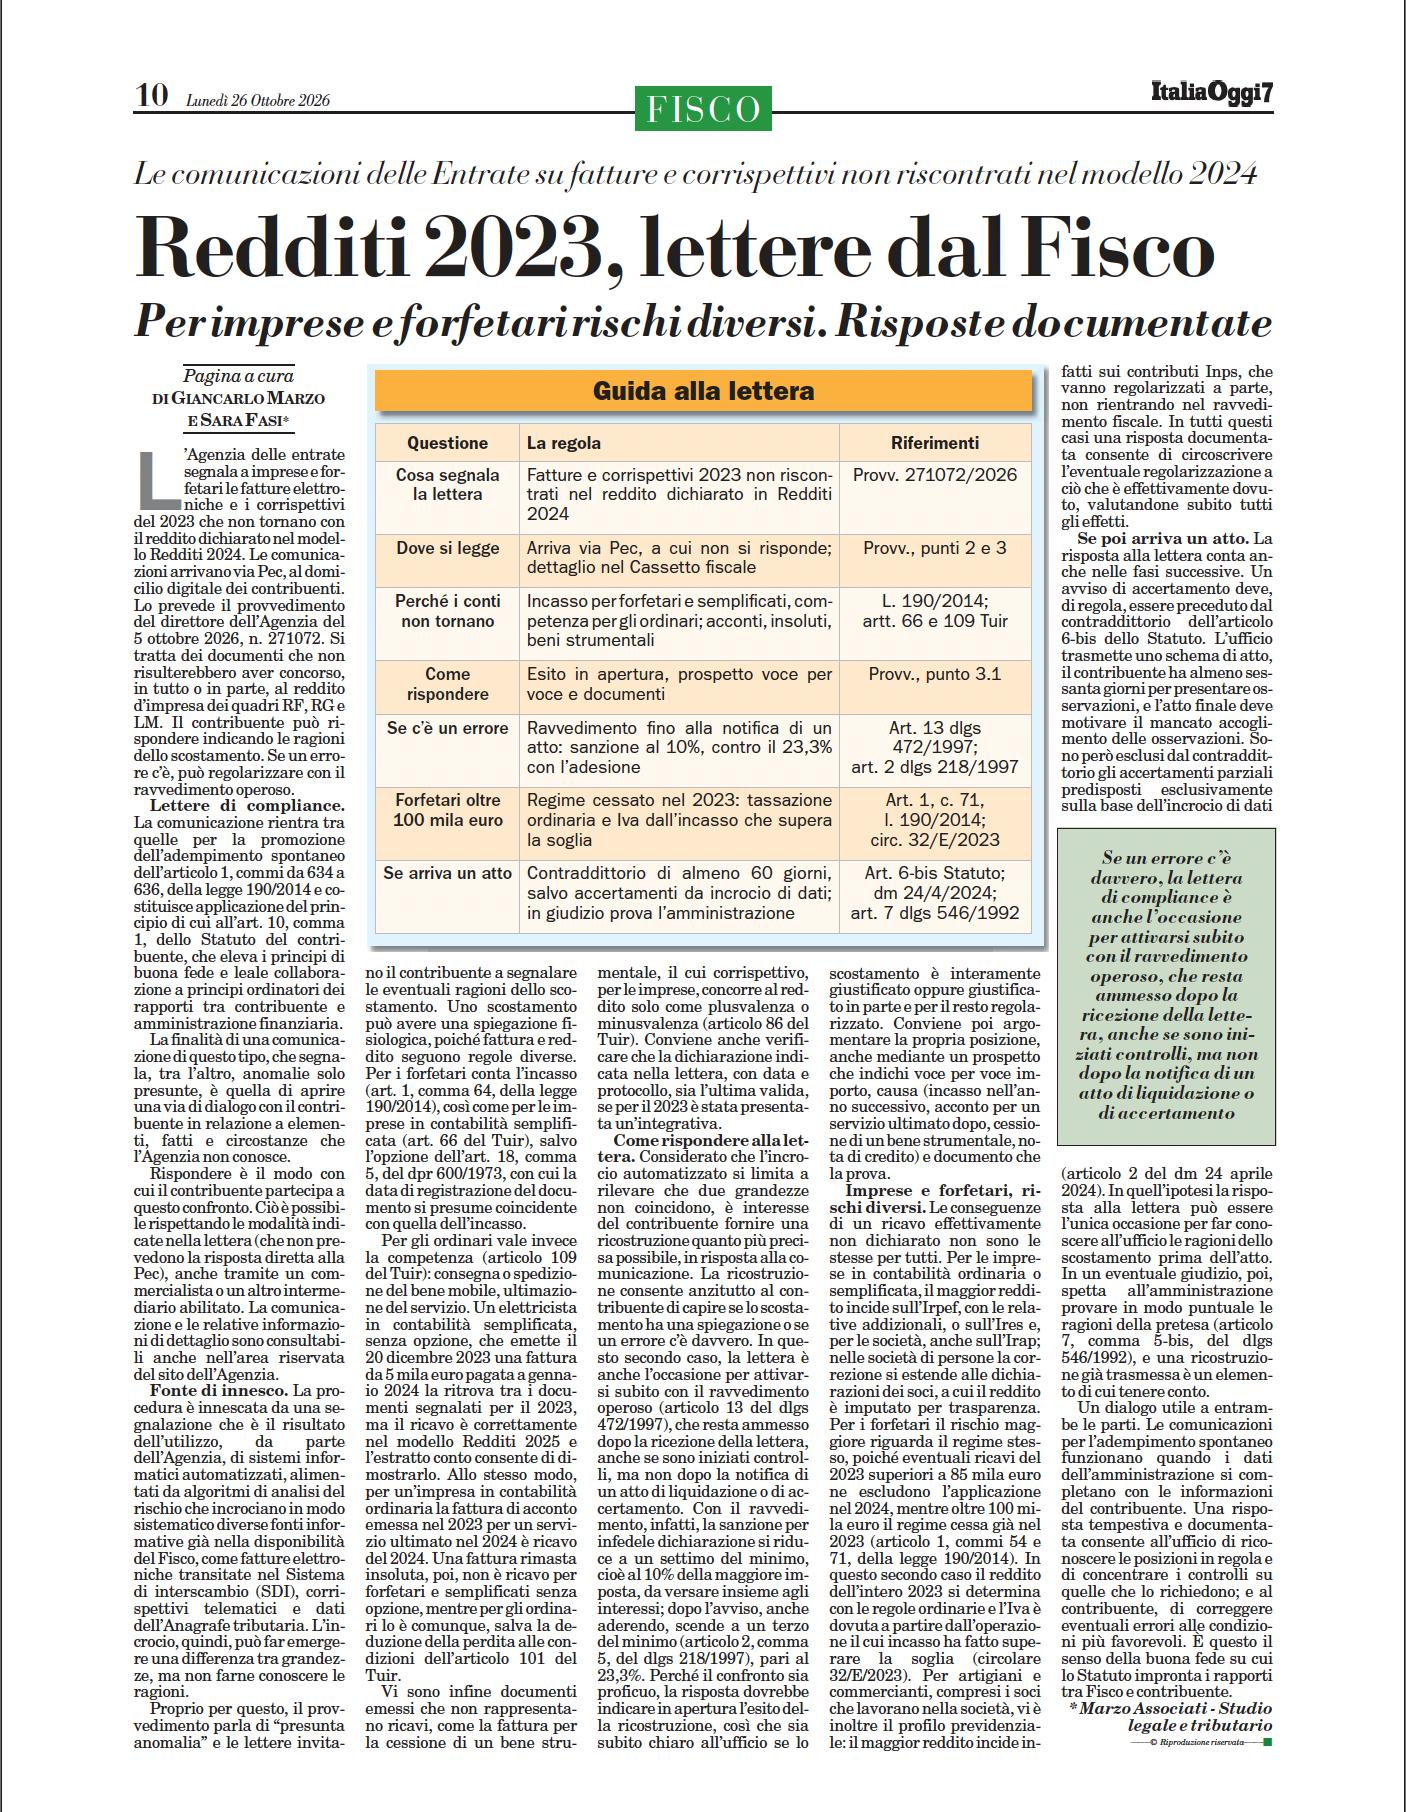
Instalment plans for tax payment notices (cartella) are the most widely used tool for managing debts with the Italian Tax Collection Agency (ADER). In 2026, it remains possible to request up to 120 monthly instalments (10 years), with stricter rules for debts above a specified threshold.
How many instalments are available
- Up to 120 instalments (120 monthly payments = 10 years) — this is the maximum standard plan.
- Up to 84 instalments for standard applications without evidence of particular hardship.
- Up to 120 instalments with documentary evidence of temporary financial hardship (ISEE, liquidity ratios).
Applications submitted in 2026 are subject to the rules introduced by D.Lgs. 110/2024 reforming tax collection, which provided for a gradual extension of plans based on the year of application.
How to submit an application
The application is submitted online through the secure area of the ADER website, or through an authorised intermediary (accountant, tax lawyer). For debts of up to €120,000, approval is automatic and no documentation is required. Above this threshold, the application must include the ISEE, liquidity indicators and details of the financial position of the business or professional.
When an instalment plan lapses
A plan lapses if a number of instalments remain unpaid (even if not consecutive), with that number varying according to the year in which the plan was granted:
- 5 instalments for plans granted in 2025-2026 (current rule).
- 8 instalments for earlier plans (previous rule).
Lapse reinstates the unpaid portion of the original debt, reactivates precautionary measures (vehicle restrictions, mortgages) and prevents a new instalment plan from being obtained for the same amounts due (subject to exceptions).
Effects of an instalment plan on other mechanisms
On limitation periods
Submitting an application for an instalment plan constitutes an acknowledgement of the debt under art. 2944 c.c. and interrupts the limitation period: the period starts running again from the date of the application. For this reason, before arranging payment by instalments, it is essential to check whether the debt is already time-barred: an instalment plan for a time-barred debt crystallises that debt.
On pending appeals
An instalment plan does not automatically entail withdrawal of an appeal. It is possible to arrange payment by instalments to avoid precautionary measures while continuing the proceedings. If a favourable judgment is issued, instalments already paid must be refunded.
On discounted settlement schemes
Joining a discounted settlement scheme for the same amounts due terminates the existing instalment plan, and the new preferential plan applies. Amounts already paid are not lost: they are credited against the outstanding debt.
On precautionary measures
An instalment plan with which the taxpayer is complying blocks attachments, vehicle restrictions and mortgages. A new mortgage or vehicle restriction registered while the instalment plan is being complied with may be challenged.
When payment by instalments is NOT advisable
- When the debt is already time-barred: it is preferable to seek statutory suspension or lodge an appeal.
- When the tax payment notice has substantive defects (invalid service, failure to serve the underlying notice): it is preferable to challenge it.
- When it is certain that the plan cannot be sustained: lapse reinstates the full debt.
- When a discounted settlement scheme that would eliminate penalties and interest is imminent.
A mixed strategy: paying some amounts by instalments and challenging others
The extract from the tax collection register lists all tax payment notices issued against the taxpayer. A developed strategy distinguishes between the amounts due: those that are certain and well documented are paid by instalments, those with well-founded grounds for challenge are appealed, and statutory suspension is sought for those that are time-barred. The Firm follows this approach to avoid crystallising debts that could be cancelled.
Frequently Asked Questions
Can I obtain an instalment plan even if a previous one has lapsed?
Yes, by submitting a new application for amounts not covered by the previously lapsed plan, or by regularising the debt under the lapsed plan in accordance with the rules of the decree implementing the reform.
What happens if I receive a new tax payment notice during an instalment plan?
The new tax payment notice is separate. The new amounts due can also be paid by instalments, by submitting a separate or combined application. The overall plan cannot exceed 120 months for each individual amount due.
Does an instalment plan block attachment?
Yes, but only if it is granted before attachment or, if notice of attachment has already been served, if the court grants a simultaneous application for a stay. It is preferable to arrange an instalment plan before notice of attachment is served on the bank.
The Firm Marzo Associati in Rome assists taxpayers and businesses in assessing instalment plans as part of an overall strategy for managing debt with ADER, including limitation periods, appeals and discounted settlement schemes. Request a technical consultation to review your extract from the tax collection register.