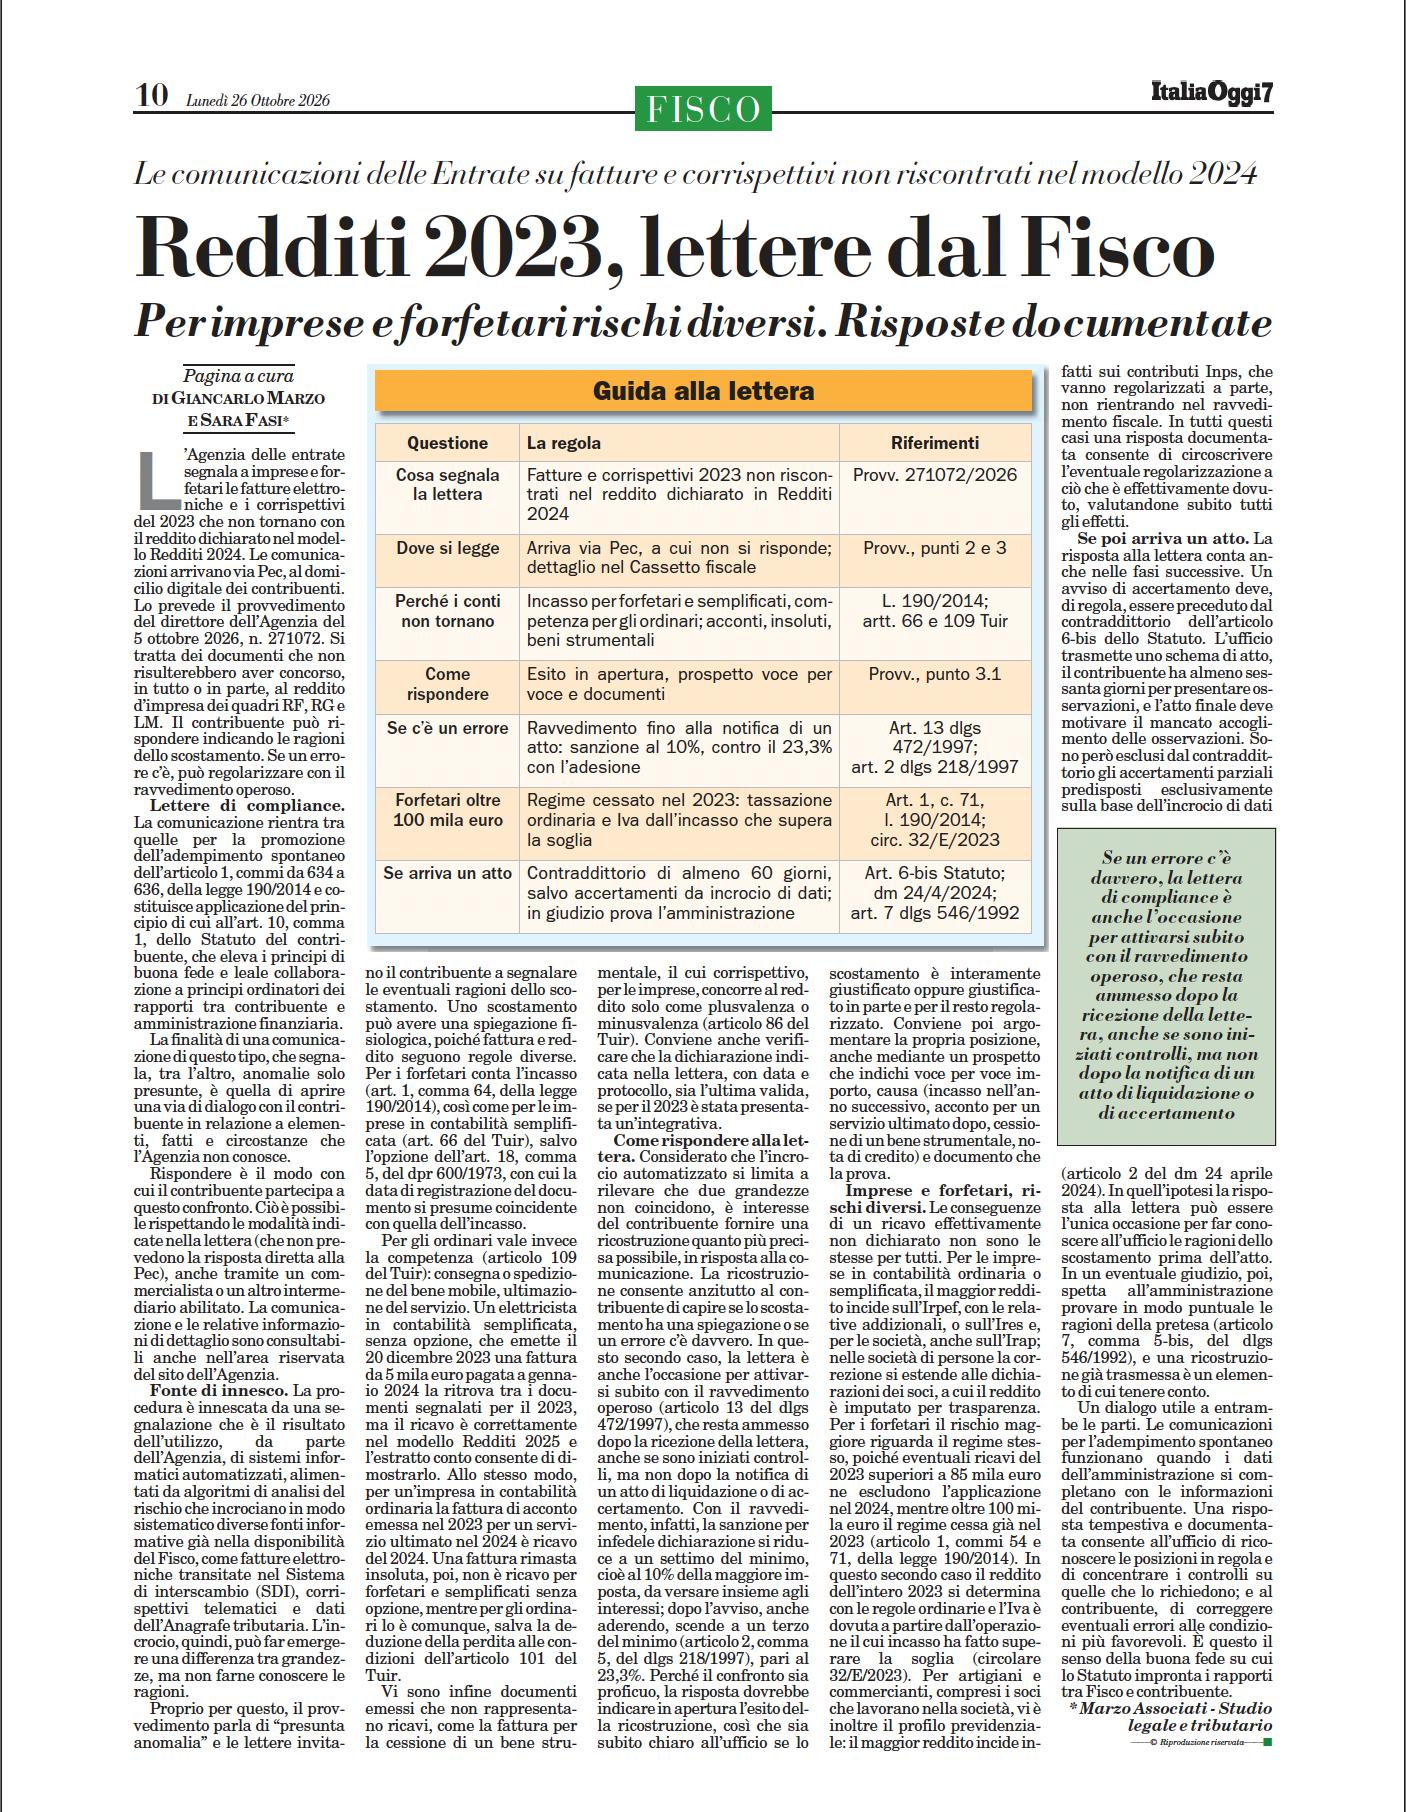
Key points: you cannot choose simply not to pay a tax payment notice (cartella), but there are six lawful ways to cancel, reduce or suspend it: check the limitation period, lodge an appeal with the Tax Court (Corte di Giustizia Tributaria) within 60 days, submit a self-correction request (autotutela) in the event of a manifest error, apply to pay by instalments (up to 120 instalments), consider the 2026 quinquies tax debt settlement scheme and obtain suspension of payment pending judgment. Each has specific conditions: choosing the wrong procedure can result in the loss of subsequent remedies.
1. Check the limitation period: an underestimated tool
A tax payment notice (cartella) may be time-barred. The limitation period varies according to the type of debt:
- 5 years for personal income tax (IRPEF), VAT, corporate income tax (IRES), IRAP (Italian Supreme Court (Corte di Cassazione), Joint Divisions (Sezioni Unite), 23397/2016 and established case law);
- 5 years for administrative penalties, road traffic fines and social security contributions;
- 10 years for local taxes according to certain minority interpretations (the case law of the Italian Supreme Court (Corte di Cassazione) now tends towards the five-year period);
- 3 years for vehicle tax.
The period runs from service of the notice or from the last act interrupting it (demand for payment, vehicle restriction, mortgage registration). If the Collection Agent has not taken valid steps within the period, the debt is time-barred and must be declared so by the tax judge. Note: the limitation defence does not operate automatically — it must be raised by way of an appeal or, at the enforcement stage, an objection.
Practical tools: request an extract from the tax collection register from the Italian Tax Collection Agency (ADER) (free of charge, online or at an agency office) to reconstruct the history of each notice and identify periods without acts interrupting the limitation period.
2. Appeal to the Tax Court (Corte di Giustizia Tributaria) within 60 days
If the notice contains substantive or formal defects, the main remedy is an appeal before the First-instance Tax Court (Corte di Giustizia Tributaria) within 60 days of service. The most frequent grounds on which appeals are upheld are:
- Failure to serve the underlying instrument properly (tax assessment notice, tax collection register entry): the Italian Supreme Court (Corte di Cassazione) requires strict proof of proper service;
- Defects in the statement of reasons: the notice must state the origin of the debt, interest, penalties and collection fee intelligibly;
- Calculation errors or duplication of amounts already paid;
- Expiry of the statutory deadline for exercising assessment powers or entering the debt in the tax collection register;
- Breach of the right to be heard in advance (art. 6-bis of the Taxpayer's Charter, since 2024).
An appeal does not automatically suspend collection: an express application for interim suspension must be made to the judge (art. 47 D.Lgs. 546/1992), demonstrating fumus boni iuris and the risk of serious harm.
3. Self-correction request (autotutela): applying directly to the authority
Where the notice contains a manifest error (amounts already paid, duplicate entries, an incorrect addressee, an evidently expired limitation period), it is possible to seek cancellation through a self-correction request (autotutela) addressed to the taxing authority (the Italian Revenue Agency (Agenzia delle Entrate) for state taxes, the municipality for IMU/TARI), with a copy to the Italian Tax Collection Agency (ADER). Since 2024, under the new art. 10-quater of the Taxpayer's Charter, action on a self-correction request (autotutela) has been mandatory in cases of manifest error, and a refusal may be challenged.
Practical limitations: a self-correction request (autotutela) does not suspend the 60-day period for a judicial appeal. It should always be submitted in parallel with, and never instead of, an appeal, except where the error is evident and the office is cooperative.
4. Payment by instalments: spreading payments to avoid attachment
Payment by instalments does not cancel the debt but suspends enforcement action (vehicle restrictions, mortgage registrations, attachments) and prevents new action. The conditions for 2026 are:
- Up to €120,000: automatic payment plans of up to 84 monthly instalments (7 years), without any requirement to document financial difficulty;
- Over €120,000 or for plans of up to 120 instalments (10 years): temporary financial difficulty must be documented through ISEE, financial statements and liquidity ratios (for businesses);
- Loss of entitlement: failure to pay 8 instalments, even if not consecutive, terminates the plan and prevents an application for a new one for the same debt.
Payment by instalments is a tactical choice: it suspends enforcement measures but entails acknowledgement of the debt, interrupts the limitation period and therefore makes it more difficult to challenge the notice later. It should be considered only after establishing that an appeal would not be appropriate.
5. The 2026 quinquies tax debt settlement scheme: who is eligible
The quinquies tax debt settlement scheme, introduced by the 2026 Budget Law, allows notices referred to the Italian Tax Collection Agency (ADER) up to 31 December 2023 to be settled by paying only the principal and statutory interest, without penalties or collection fees. Main features:
- Amount payable: outstanding principal + statutory interest + service and procedural costs;
- Cancellation of penalties and collection fees: the average reduction is around 30–40% of the amount entered in the tax collection register;
- Payment: in a lump sum or in up to 18 instalments (3 years), with the first instalment due by July 2026 (precise dates to be set by the implementing ministerial decree);
- Effects: immediate suspension of vehicle restrictions, mortgage registrations and attachments from the date of joining the scheme.
The settlement scheme is a practical opportunity but is not always advantageous: if the debt is clearly time-barred or capable of cancellation through a self-correction request (autotutela), joining means giving up more far-reaching defences. A case-by-case assessment is essential.
6. Statutory suspension and parallel litigation
Art. 1, paragraphs 537–543, of L. 228/2012 provides for mandatory statutory suspension of collection if, within 60 days of service of the notice, the taxpayer declares in a documented application that the debt has already been paid, is time-barred, has been discharged following a self-correction request (autotutela) or is covered by a favourable judgment. The Collection Agent must suspend collection and forward the application to the taxing authority, which has 220 days to confirm or reject it. If it does not reply, the debt is automatically cancelled.
This is a powerful, little-known remedy, to be used in parallel with every other procedure where the documentary requirements are met.
Mistakes to avoid
Three recurring mistakes undermine any strategy:
- Allowing the 60-day period to expire: the notice becomes final and the only remaining remedies are the limitation defence and a self-correction request (autotutela) for partial cancellation;
- Paying the first instalment under a payment plan without first checking whether the notice can be challenged: payment acknowledges the debt and interrupts the limitation period;
- Joining the settlement scheme for debts that are already time-barred: a dead debt is replaced with a live, final debt.
Frequently Asked Questions
What happens if I completely ignore a tax payment notice (cartella)?
After 60 days from service, the notice becomes final. The Italian Tax Collection Agency (ADER) may register an administrative vehicle restriction (with 30 days' prior notice), register a mortgage (for debts exceeding €20,000), or attach salary, pension or bank account funds. The limitation period continues to run and must still be raised as a defence in court.
Can I stop an attachment that has already been served?
Yes, by lodging an objection to enforcement before the ordinary courts (for defects in the attachment itself) or an objection to enforcement measures within 20 days. To challenge the merits of the debt, an urgent application for interim relief must be made to the Tax Court (Corte di Giustizia Tributaria). Interim suspension may be obtained within a few days where there is a serious and immediate risk.
Are tax payment notices (cartelle) cancelled after a certain number of years?
They are not cancelled automatically: they become time-barred, but only if no acts interrupting the limitation period (demands for payment, mortgage registrations, vehicle restrictions) have been served during that period (5 or 10 years). The limitation defence must always be asserted in court or through an application for statutory suspension under L. 228/2012.
Is the 2026 quinquies tax debt settlement scheme advantageous for everyone?
No. It is advantageous where the debt cannot be challenged and the aim is to avoid penalties and collection fees. It is not advantageous if the notice contains defects (failure of service, an expired limitation period, calculation errors): in those cases, an appeal may eliminate the debt rather than merely secure a "discount". A preliminary assessment with a tax lawyer is always recommended.
How much does legal assistance to challenge a notice cost?
A preliminary analysis of the extract from the tax collection register and the notice involves limited costs (a one-off consultation). An appeal before the Tax Court (Corte di Giustizia Tributaria) follows the fee parameters under DM 55/2014 and is proportionate to the value of the dispute; in many cases, costs can be recovered if the appeal succeeds. The Firm Marzo Associati always provides a transparent fee estimate before accepting instructions.
Have you received a tax payment notice (cartella)?
The deadline for challenging it is only 60 days from service. A timely analysis of the notice and the extract from the tax collection register can make the difference between a final debt and one capable of cancellation. The Firm Marzo Associati assists taxpayers and businesses throughout Italy with appeals against tax payment notices (cartelle), objections to administrative vehicle restrictions and assistance in tax litigation before the Tax Courts (Corti di Giustizia Tributaria).