
Immediate Obligation for Minor Heirs to File Income Tax Returns: Clarifications from the Italian Revenue Agency (Agenzia delle Entrate)
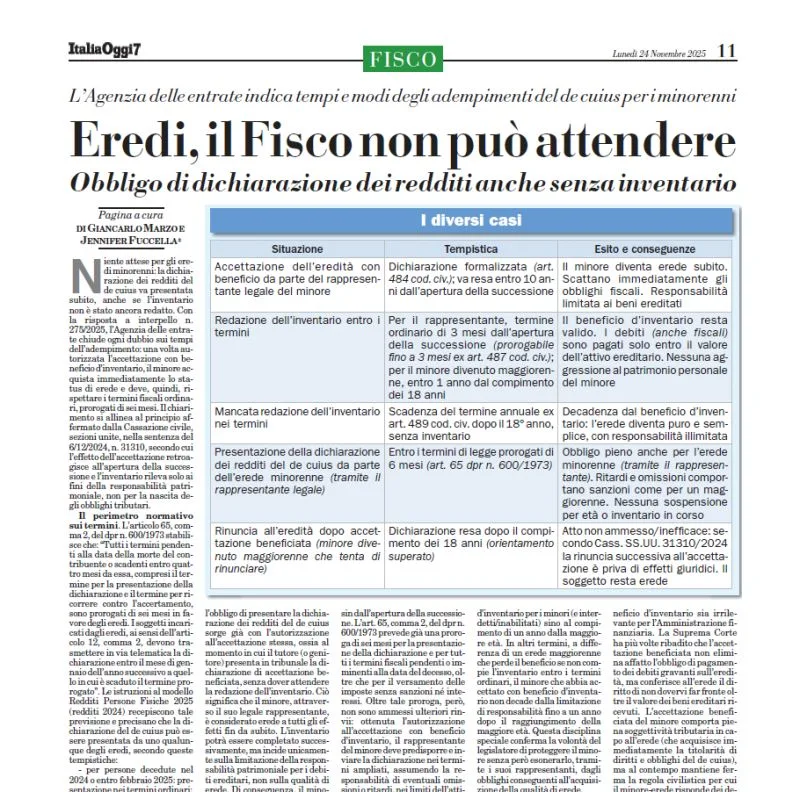
The Italian Revenue Agency (Agenzia delle Entrate), through tax ruling (risposta a interpello) n. 275/2025, has provided a key clarification regarding the timing and manner of compliance with the tax obligations imposed on minor heirs. The tax administration's position is unequivocal: the tax authorities do not allow prolonged delays in meeting these obligations.
Status as a Minor Heir and Immediate Tax Compliance
For minors, acceptance of an inheritance with benefit of inventory is mandatory by law. As soon as such acceptance is authorised, the minor immediately acquires the status of heir. Consequently, the minor must comply with the ordinary tax deadlines for filing the income tax return of the deceased; the only concession granted is the six-month extension provided for by art. 65 of d.p.r. n. 600/1973.
No Suspension Pending Preparation of the Inventory
The obligation to file the income tax return arises as soon as authorisation to accept the inheritance is obtained. The Italian Revenue Agency (Agenzia delle Entrate) clarifies that this obligation must be fulfilled (through the minor's legal representative) without waiting for the inventory to be actually prepared. The inventory, in fact, affects only the limitation of the heir's financial liability for inherited debts (known as liability intra vires), but in no way suspends the status of taxpayer or the associated filing obligations.
This approach is consistent with the principles established by the Joint Divisions (Sezioni Unite) of the Italian Supreme Court (Corte di Cassazione) (judgment n. 31310/2024), which reaffirm that acceptance takes effect retrospectively from the opening of the succession for the purposes of the arising of tax obligations.
Conclusions
In summary, for minor heirs, acceptance of an inheritance with benefit of inventory results in the immediate acquisition of the status of heir and, consequently, the obligation to file the income tax return of the deceased within the ordinary deadlines (extended by six months), without awaiting completion of the inventory.


