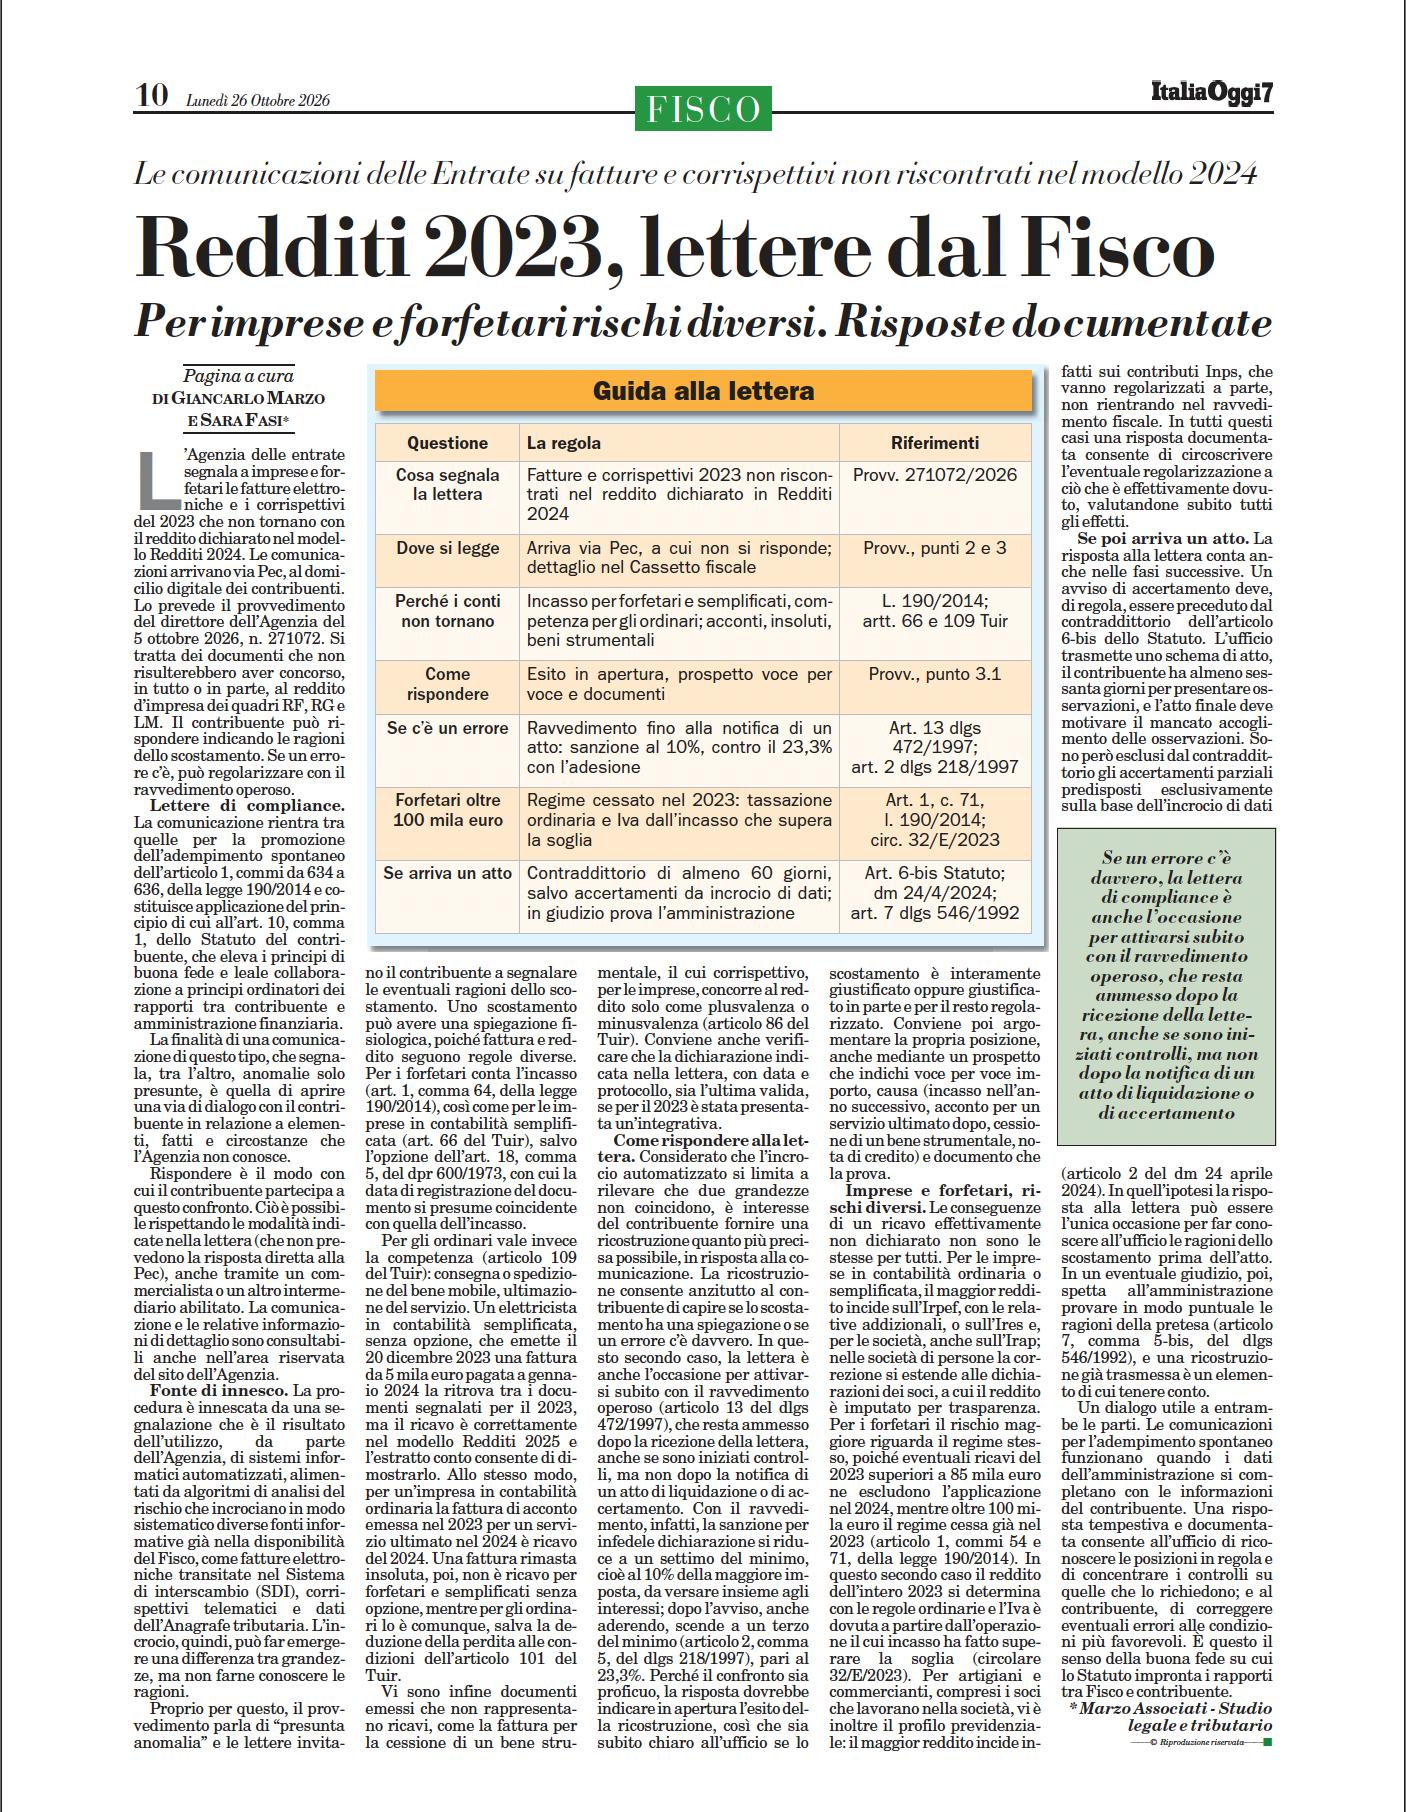
Limitation of a tax payment notice (cartella) is an effective tool for cancelling old debts with the Italian Tax Collection Agency (ADER). The periods range from 5 to 10 years depending on the type of claim entered on the collection roll. In 2026, the case law of the Italian Supreme Court (Corte di Cassazione) confirms the approach favourable to taxpayers regarding social security contributions, administrative penalties and local taxes.
How many years is the limitation period for a tax payment notice (cartella)?
There is no single limitation period: it depends on the nature of the claim entered on the collection roll, not on the notice itself. A tax payment notice (cartella) is a collection instrument and does not constitute a new enforceable title: the limitation period remains that applicable to the original claim.
- 5 years — social security and welfare contributions (INPS (Italian social security institute), INAIL), local taxes (IMU, TARI, TASI), non-tax administrative penalties (Road Traffic Code), RAI television licence fee, monetary tax penalties under art. 20 D.Lgs. 472/1997.
- 10 years — state taxes (personal income tax (IRPEF), corporate income tax (IRES), VAT, registration tax), subject to minority judicial approaches applying the 5-year period to these as well in the absence of a final judgment.
- 3 years — vehicle tax in certain regions that have adopted specific periods.
Which acts interrupt the limitation period?
The limitation period is interrupted whenever the creditor serves the debtor with a formal notice of default or an act capable of interrupting the period. Following interruption, the full period starts running again from the date of the act.
- Service of the tax assessment notice or the underlying instrument.
- Service of the tax payment notice (cartella).
- Service of a payment demand under art. 50 D.P.R. 602/1973.
- Service of advance notice of an administrative vehicle restriction or registration of a mortgage.
- Service of an attachment order.
- A judicial claim brought by the creditor.
- Acknowledgement of the debt by the debtor, including implicit acknowledgement (an application to pay by instalments or for a discounted tax debt settlement).
Please note: an application to pay by instalments or for a discounted tax debt settlement submitted without a preliminary assessment resets the limitation period and crystallises the debt. It is therefore essential to review the overall position first.
How to calculate the period in practice: an example
A tax payment notice (cartella) for IMU for 2014 served on 10 March 2017. A local tax, with a five-year limitation period. The 5 years run from 10 March 2017: without any interrupting acts, the claim becomes time-barred on 10 March 2022. If the taxpayer receives a payment demand relating to that notice in 2026, they may plead limitation and seek its cancellation.
A tax payment notice (cartella) for IRPEF for 2010 served on 8 September 2014. A state tax, with a ten-year limitation period. Without any interrupting acts, the claim becomes time-barred on 8 September 2024. If ADER serves notice of an administrative vehicle restriction today, the debt is time-barred and the restriction may be set aside.
How to invoke limitation: the available procedures
Limitation does not operate automatically: it must be pleaded by the debtor. There are three complementary procedures.
1. Statutory suspension under L. 228/2012
A free and effective procedure. A statement supported by documentary evidence is submitted to ADER, which forwards it to the creditor authority. The authority has 220 days to respond: failing this, the debt is automatically cancelled through deemed approval by silence.
2. Appeal to the Tax Court (Corte di Giustizia Tributaria)
Within 60 days of service of the instrument (tax payment notice (cartella), payment demand, vehicle restriction, mortgage) for taxes. Limitation is pleaded among the grounds of appeal, together with an application for interim suspension under art. 47 D.Lgs. 546/1992.
3. Objection to enforcement under art. 615 c.p.c.
For social security contributions (Labour Court (Tribunale del Lavoro)) or non-tax administrative penalties (Justice of the Peace or Ordinary Court (Tribunale Ordinario)).
What is needed to establish limitation?
A limitation defence requires a precise chronological reconstruction: an up-to-date extract from the collection roll, copies of all instruments served, and certificates of service to verify their validity and effectiveness in interrupting the limitation period. Invalid service, besides potentially leading to the instrument being set aside, does not interrupt the limitation period.
Frequently Asked Questions
Can a tax payment notice (cartella) that was never served be time-barred?
Yes. Indeed, where service has not taken place, the limitation period runs from service of the underlying instrument (tax assessment notice or collection roll), without having been interrupted by the tax payment notice (cartella). This is often discovered by examining the extract from the collection roll.
Can attachment still be pursued under a time-barred tax payment notice (cartella)?
ADER could proceed if limitation is not pleaded: it is therefore essential to act promptly by seeking statutory suspension or lodging an appeal as soon as collection instruments are received.
Can I invoke limitation directly with ADER?
Yes, by applying for statutory suspension under L. 228/2012. This is free of charge and in many cases resolves the position without the need for a judicial appeal.
The Firm Marzo Associati in Rome assists taxpayers, businesses and professionals in analysing their debt positions with the Italian Tax Collection Agency (ADER) and in initiating limitation, suspension and appeal procedures. Request a technical consultation to review your extract from the collection roll.