
Italian Supreme Court (Corte di Cassazione) 1667/2026: Attachments to Notices to Shareholders of Closely Held Companies Are Not Mandatory
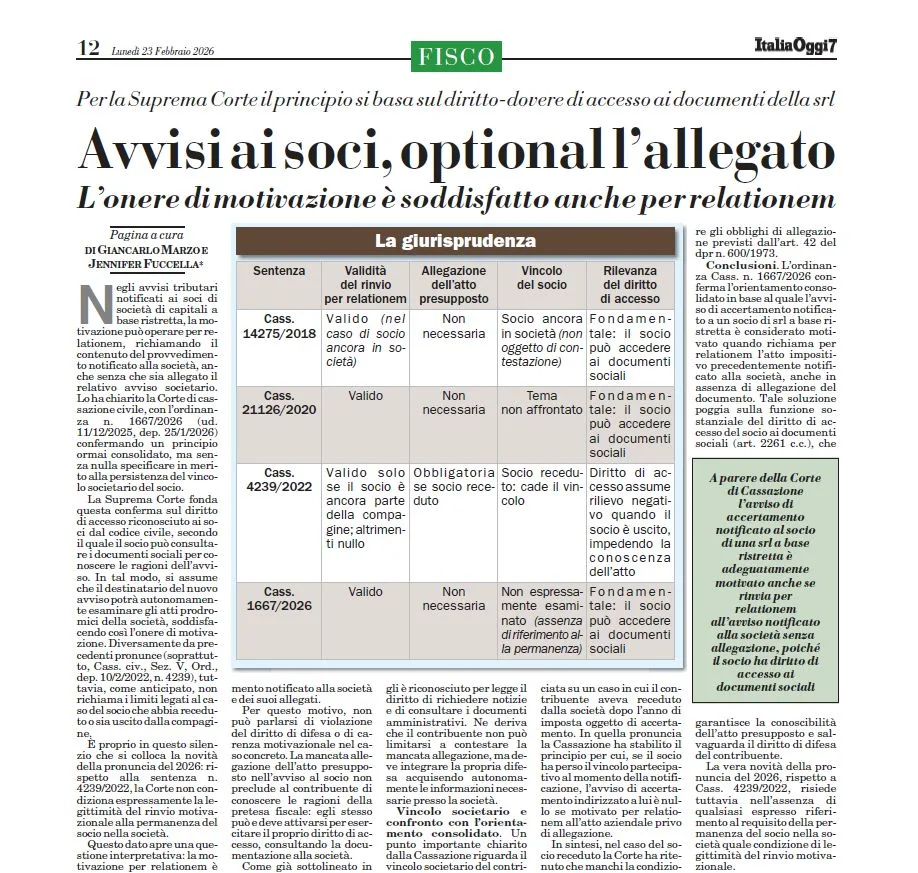
Order no. 1667/2026 of the Italian Supreme Court (Corte di Cassazione), filed on 23 February 2026, clarified an important aspect for all closely held companies limited by shares concerning tax notices served on shareholders.
Reasons Given by Reference in Tax Notices to Shareholders
In tax notices served on shareholders of SRLs, the tax authorities are not required to physically attach the underlying decision, namely the instrument that gave rise to the assessment. It is sufficient for the notice to refer clearly to that decision and for the shareholder to be guaranteed an effective opportunity to consult it.
This principle is based on the right and duty to access company documents, provided for by Articles 2294 and 2315 of the Civil Code and Article 42 of DPR 600/1973.
In practice, the duty to state reasons is satisfied "by reference": a simple reference to the instrument already served on the company is considered sufficient.
Practical Implications of the Judgment
This ruling brings several changes in practice:
- For professional firms: the risks of notices being invalid owing to the failure to attach the underlying instrument are significantly reduced.
- For closely held SRLs: as long as a shareholder remains a member of the company, they always have the right to access company documents, allowing the Agency merely to refer to the underlying instrument.
- A shareholder who has left the company also retains the right of access for the periods during which they were a shareholder.
The Right to Access the Underlying Instrument
The Court specified that «A tax assessment notice served on a shareholder of a closely held SRL is adequately reasoned even if it does not reproduce the attachment by reference, provided that access to the underlying instrument and the opportunity to access company documents are ensured».
This decision confirms and reinforces previous case law (Cass. 14275/2018, 21126/2020 and 4239/2022), making it clearer and more applicable in day-to-day practice.
Conclusions
Order 1667/2026 of the Italian Supreme Court (Corte di Cassazione) establishes that, in tax notices served on shareholders of closely held companies limited by shares, attaching the underlying decision is optional, provided that access to the instrument and the right to access company documents are always ensured.


